When the Appraisal Comes In Low: What Buyers and Sellers Can Actually Do
I'll admit it up front: appraisals are one of my pet peeves. In my opinion, the best proof of value is what a ready, willing buyer agrees to pay. But the lender needs an appraisal, and when it comes in low, it can stall or even kill a sale.
At a recent Tuesday training, I asked Amber Gowdy, CEO, and Michelle Massucci, COO, of Liberty Home Mortgage in Independence to explain what really happens with appraisals and what buyers, sellers and agents can actually do about a low one. Here's what they told us.
Who the appraiser works for
Lenders typically order appraisals through an appraisal management company, or AMC. The AMC assigns the appraiser and makes sure they're licensed, following the standards and staying independent. That independence is the point. Nobody is supposed to be able to pressure an appraiser into a number.
That's also why an agent can't just call the appraiser and say "use these two comps instead." Any challenge has to go through the proper channel.
How a reconsideration of value works
If the value comes in low and the buyer, seller and agents believe it's wrong, the lender can submit a reconsideration of value, often called an ROV. The agent helps fill it out with better comparable sales, the reasons they're better and any adjustments the appraiser may have missed. The lender sends it to the AMC, which passes it to the appraiser.
Under Fannie Mae's ROV requirements, a borrower can request one ROV for each appraisal report, so make it count. Michelle told us Liberty also asks the appraiser to explain why the comps in the ROV don't support the value, not just to say no. On a recent appraisal that came in $50,000 short, that's exactly what they pushed for.
What I've seen in 19 years
In 19 years in this business, I've gotten an appraiser to change a value exactly once. They had missed a half bath. When we pointed it out, they added $2,500, which happened to be exactly what we were short.
The one that still bothers me was a house in Hudson. The appraiser used a comparable that needed a ton of work and backed up to the freeway. I showed a better comp, and the answer was basically, "Mine is closer, so it's better." Closer isn't always better. A gutted house next to the highway isn't the same as a well-kept home on a quiet street.
Amber's take on why appraisers rarely budge was fair. They've inspected the property, pulled the comps and made their adjustments, so it's hard for them to accept that someone who wasn't there knows better. That's why a strong ROV sticks to facts: better comps, clear adjustments and neighborhood data.
Second appraisals, desk reviews and field reviews
A second appraisal isn't automatically the answer. If two appraisals come in far apart, someone still has to decide which one to use. That can lead to:
- A desk review, where another appraiser reviews the original report and the market data without visiting the house.
- A field review, where a new appraiser goes out to the property to check the work in person.
In the end, the lender has to decide which value is best supported, without having seen the house themselves. For FHA loans, the guests explained that the lender has to show the first appraisal had material deficiencies before a second one can be ordered.
What the new federal housing law changes
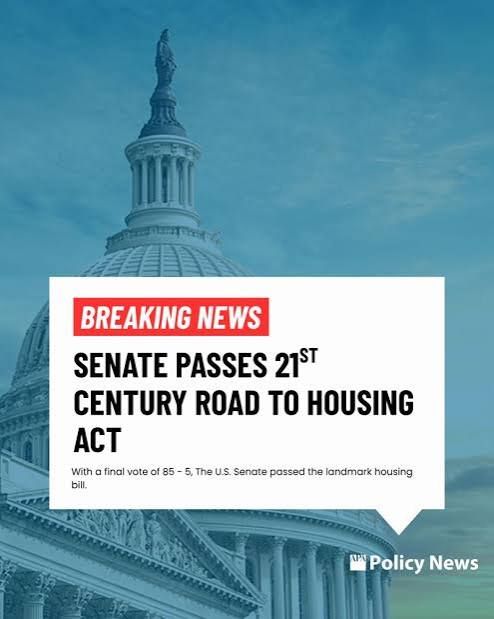
The 21st Century ROAD to Housing Act became law in July 2026. According to the National Consumer Law Center, it requires mortgage lenders to have procedures that let consumers request a second appraisal or a reconsideration of value when they believe the value may be wrong. The Appraisal Institute notes that federal regulators are directed to set consistent standards for both.
At the time of our training, the detailed rules hadn't been released yet. The guests were hopeful the result will be a clearer process and more options when an appraisal is clearly wrong. Until those rules come out, the current process still applies.
Too high can be a problem, too
Here's something most people never hear about. An appraisal can also come in too high. Fannie Mae's Collateral Underwriter gives each appraisal a risk score from 1.0 to 5.0, with higher numbers meaning higher risk. Amber said that when scores come in around 4.2 to 4.5, they may be asked for a field review to support the value, and that review can bring the number down.
What buyers and sellers can do
- Sellers: Price with real comparable sales. A price you can support makes for an appraisal you can defend.
- Buyers: Understand your appraisal contingency and what happens if the value comes in short: renegotiate, bring cash or walk away.
- Both: If you challenge a value, do it through the lender, with facts, not frustration.
- Everyone: Talk early about the plan if the appraisal comes in low, before emotions run high.
Buying or selling soon?
Appraisals are one of the places where an experienced agent and a responsive lender earn their keep. If you're buying or selling in Northeast Ohio, schedule a time with me or someone on our team at 21mike.com.
For mortgage questions or financing guidance, get in touch with Amber Gowdy, CEO, at 330-714-0831 or Michelle Massucci, COO, at 440-813-6280 at Liberty Home Mortgage.
Want to see the full session? Watch our Tuesday training with Liberty Home Mortgage.
Mike Ferrante
The Mike Team at LPT Realty
www.21mike.com
Google Business Profile: https://g.page/r/CSQoYzel0Z68EAE
+1 (216) 373-7727
Categories
Recent Posts