Why First-Time Buyers in Aurora Need to Budget for an HOA Before They Budget for a Mortgage
Why First-Time Buyers in Aurora Need to Budget for an HOA Before They Budget for a Mortgage
When first-time buyers start looking at Aurora, most picture a house, a yard, and a mortgage payment. What catches a lot of them off guard is how many Aurora homes come with a homeowners association.
That isn't a bad thing. But an HOA is a financial and legal commitment on top of your mortgage, and it changes how you should budget and what you should ask before you write an offer. Here's how to plan for it, and how Ohio's down payment assistance can help you get into the right home.
The HOA question most first-time buyers don't ask
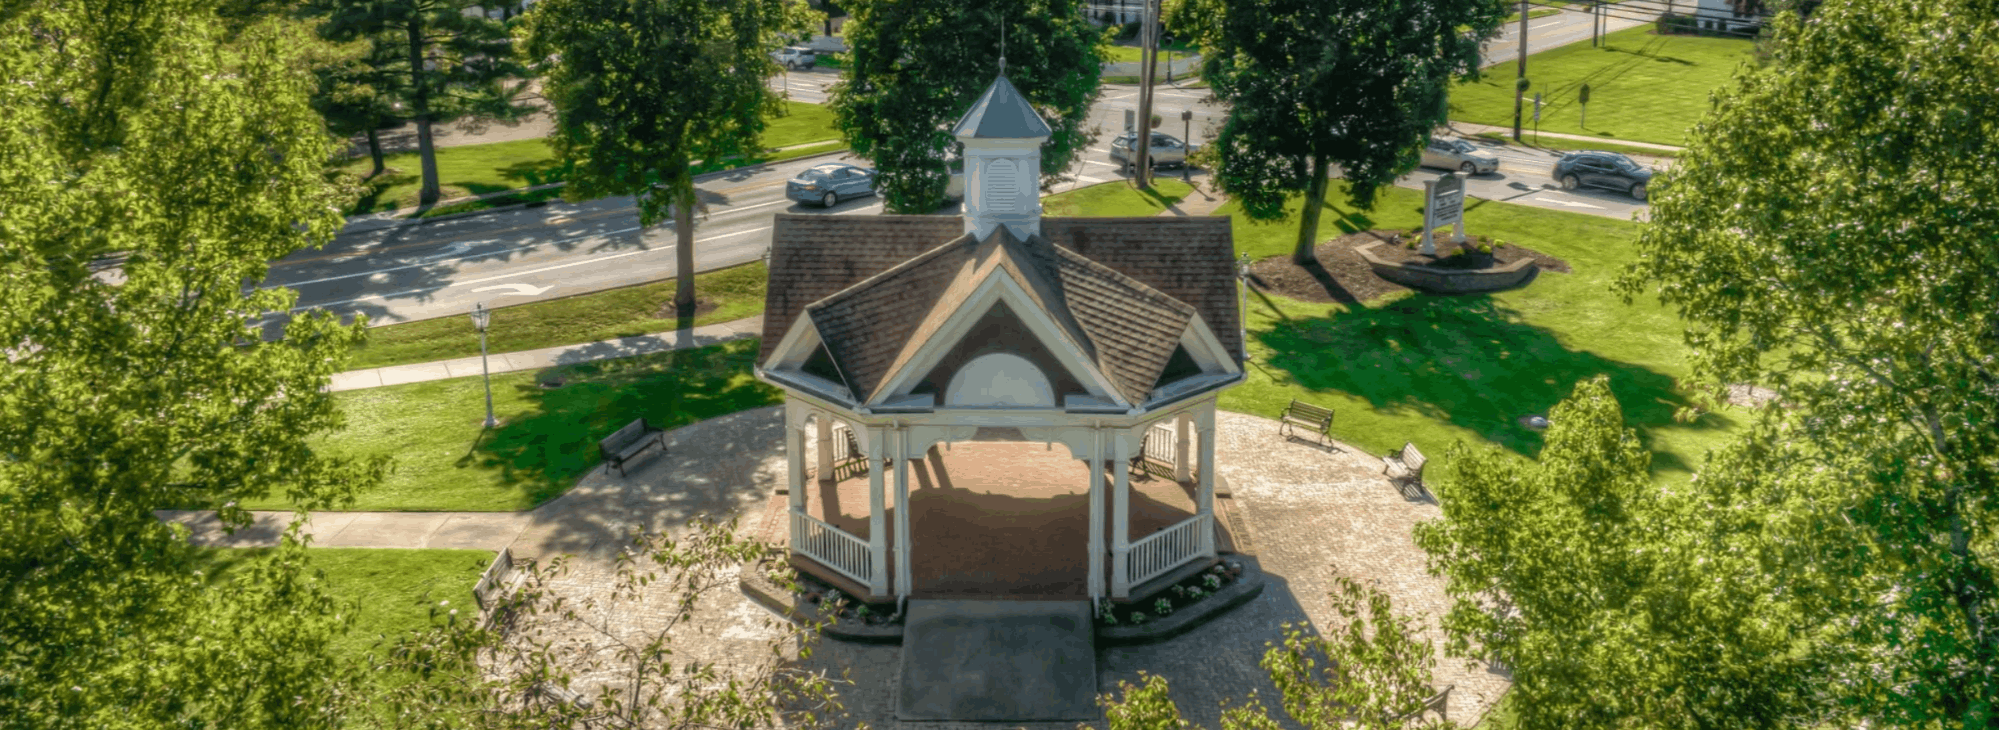
Aurora Shores is a good example. According to the Aurora Shores Homeowners' Association, the community has 887 homes spread across the City of Aurora and the Village of Reminderville, built around a private 340-acre lake. Residents get lake access, two beaches, two pools, tennis and pickleball courts, and a clubhouse. The association is run by a Board of Trustees.
Those amenities are a big part of the appeal. They also cost money to maintain, and that's what your dues pay for. Aurora also has condo and townhome communities with their own associations, which can be a lower-maintenance first step into the market.
One more Aurora Shores detail worth knowing: depending on which side of the line a home sits on, children attend either Aurora City Schools or Twinsburg City Schools. Same neighborhood, different school district, and possibly a different tax bill.
What an HOA does to your monthly number
Many first-time buyers budget for principal, interest, taxes, and insurance, then treat HOA dues as an afterthought. That's backwards. Dues are a required, recurring payment, just like your mortgage. You can't opt out because you mow your own lawn or never use the pool.
Your lender will count the monthly dues in your debt-to-income ratio, so they can change how much home you qualify for. Before you get attached to a home in an association, ask for two numbers: the current dues and whether any special assessment is pending or planned. Both belong in your budget from day one, not after you're under contract.
Read the HOA documents like an owner
Our team's approach is to think like an owner, and that means reading what you're actually buying into, not just the dues amount:
- The budget and reserves. A thin reserve fund can mean a large special assessment soon after you move in.
- Exterior rules. Fences, sheds, paint colors, and additions may need approval.
- Rental rules. If you might rent the home out someday, find out now whether that's allowed.
- Recent meeting minutes. They often show what big projects or disputes are coming.
For condos, your lender will also review the association's finances and insurance. Don't waive your time to review HOA documents just to win a competitive listing. That's one of the easiest ways for a first-time buyer to inherit a problem.
How OHFA down payment assistance works
The Ohio Housing Finance Agency offers down payment assistance through approved lenders. According to OHFA's down payment assistance page, the program provides:
- 3 percent of the purchase price on a conventional loan, or 3.5 percent on a government loan (FHA, VA, or USDA)
- Money you can use for your down payment, closing costs, and prepaid expenses
- Assistance that's forgiven after seven years. If you sell before then, you repay it.
On a $300,000 purchase, that's about $9,000 with a conventional loan or $10,500 with a government loan. OHFA requires a minimum credit score of 640 for conventional, USDA, and VA loans and 650 for FHA, plus a free homebuyer education course. Income and purchase price limits vary by county and household size, so confirm your eligibility with an OHFA-approved lender.
The program works on single-family homes and condos, so it can free up cash for a dues cushion or moving costs.
Property taxes are part of the same math
Aurora is in Portage County, and your tax bill depends on the specific parcel and taxing district. As the Aurora Shores example shows, homes close together can fall in different school districts. Look up the actual tax history for any home you're serious about on the Portage County Auditor's site, rather than estimating from a neighbor's bill or a city average.
One thing you won't have to plan for: Aurora doesn't require a city point-of-sale inspection, according to the Akron Cleveland Association of Realtors point-of-sale guide. You'll still want your own home inspection.
Four numbers to have before you shop
- Your estimated mortgage payment from a lender, not an online calculator
- The HOA dues and any pending assessments for communities you're considering
- The actual property taxes for the parcels you like
- The down payment assistance you actually qualify for
With those in hand, you'll shop with confidence instead of guessing. It also keeps you from falling for a home that works on paper but not in your real monthly budget.
Frequently asked questions
Can I use OHFA assistance on a condo? Yes. It can be used on a single-family home or a condo, as long as you and the property meet the program's limits.
Do I have to pay the assistance back? It's forgiven after seven years. If you sell before then, you repay it.
Are HOA dues negotiable? No. They're set by the association. What you can negotiate is the price and who pays any transfer fees at closing.
Buying your first home in Aurora?
If you're trying to make sense of Aurora's neighborhoods, HOA rules, or what you might qualify for through OHFA, I'd be glad to walk through it with you. Schedule a time with me or someone on our team at 21mike.com.
Mike Ferrante
The Mike Team at LPT Realty
www.21mike.com
Google Business Profile: https://g.page/r/CSQoYzel0Z68EAE
+1 (216) 373-7727
Categories
Recent Posts